18 September 2026
Home Loan Guide 2026: How to Get the Best Interest Rate for Your Chennai Apartment
Buying a home is a major financial commitment, and choosing the right home loan can have a significant impact on your monthly EMI and the total amount you pay over the loan period.
Home loan interest rates can vary depending on your credit profile, income, existing financial commitments, down payment, loan tenure, and the lender you choose.
For buyers planning to purchase a property in Chennai, understanding these factors can help them find a more suitable home loan interest rate in Chennai and plan their finances more effectively.
What Actually Determines Your Home Loan Interest Rate?
Home loan interest rates are not necessarily the same for every borrower. Even when two applicants purchase similar properties, the interest rate offered by a lender can differ based on their individual financial profiles.
Lenders generally consider factors such as credit score, income stability, employment or business history, existing debt obligations, loan amount, loan-to-value ratio, and the applicant's relationship with the bank.
Understanding these factors before applying can help buyers prepare a stronger loan application and compare offers more effectively instead of simply accepting the first rate quoted.
Your Credit Score Is Doing More Work Than You Think
Your credit score is an important factor lenders consider when evaluating a home loan application.
A strong credit history can demonstrate responsible repayment behaviour and may help you qualify for more competitive loan terms. A lower score may result in stricter eligibility conditions or less favourable pricing depending on the lender.
Before applying for a home loan, check your credit report for incorrect information and make sure any outstanding dues are addressed.
Maintaining timely repayments on existing loans and credit cards can also help establish a stronger credit profile over time.
Fixed vs Floating Rates — What's the Real Difference?
A fixed interest rate remains unchanged for a specified period or, depending on the loan product, for the entire applicable period. This can provide greater predictability because your interest rate is less affected by changes in market rates during the fixed period.
A floating interest rate can change based on the lender's applicable benchmark and other rate-related factors. As a result, your EMI or loan tenure may change when the applicable interest rate changes.
Floating-rate loans may offer competitive starting rates, but borrowers should be comfortable with the possibility of future rate changes.
Before selecting a loan, compare fixed, floating, or hybrid options available from the lender and consider your income stability, repayment capacity, and preference for predictable EMIs.
Loan Tenure and Its Effect on Total Interest Paid
Loan tenure has a direct impact on both your monthly EMI and the total interest paid over the life of the loan.
A longer tenure generally results in a lower monthly EMI, which can make the loan easier to manage from a monthly cash-flow perspective. However, the total interest paid over the complete loan period can be considerably higher.
A shorter tenure usually increases the monthly EMI but can reduce the overall interest paid.
Instead of automatically selecting the maximum tenure offered, buyers should compare different repayment periods using a home loan calculator and choose a tenure that balances monthly affordability with the total cost of borrowing.
Loan-to-Value Ratio and Your Down Payment
Loan-to-value, or LTV, represents the proportion of the property's value that is financed through the loan. The remaining amount is contributed by the buyer as a down payment, subject to applicable lending rules.
A higher down payment means you borrow a smaller amount relative to the property's value. This can reduce your overall loan burden and may also improve your borrowing profile with some lenders.
For example, a buyer purchasing a plot at GP Homes Aishwarya Garden who contributes a larger portion of the purchase price upfront may have a lower loan requirement compared with someone borrowing a larger proportion of the property value.
Before deciding the down payment, buyers should maintain sufficient funds for registration, documentation, interiors, moving expenses, and other applicable costs instead of using all available savings for the property purchase.
Comparing Lenders the Right Way
When comparing home loans, do not look only at the advertised interest rate.
Processing fees, legal and technical charges, prepayment conditions, administrative charges, and other applicable costs can affect the overall cost of borrowing.
Ask each lender for a complete illustration of the loan, including the applicable interest rate, EMI, processing charges, tenure, and other relevant fees.
Also check whether the quoted interest rate applies to the exact loan amount and loan-to-value ratio you require. Comparing at least two or three lenders can help you understand the available options more clearly.
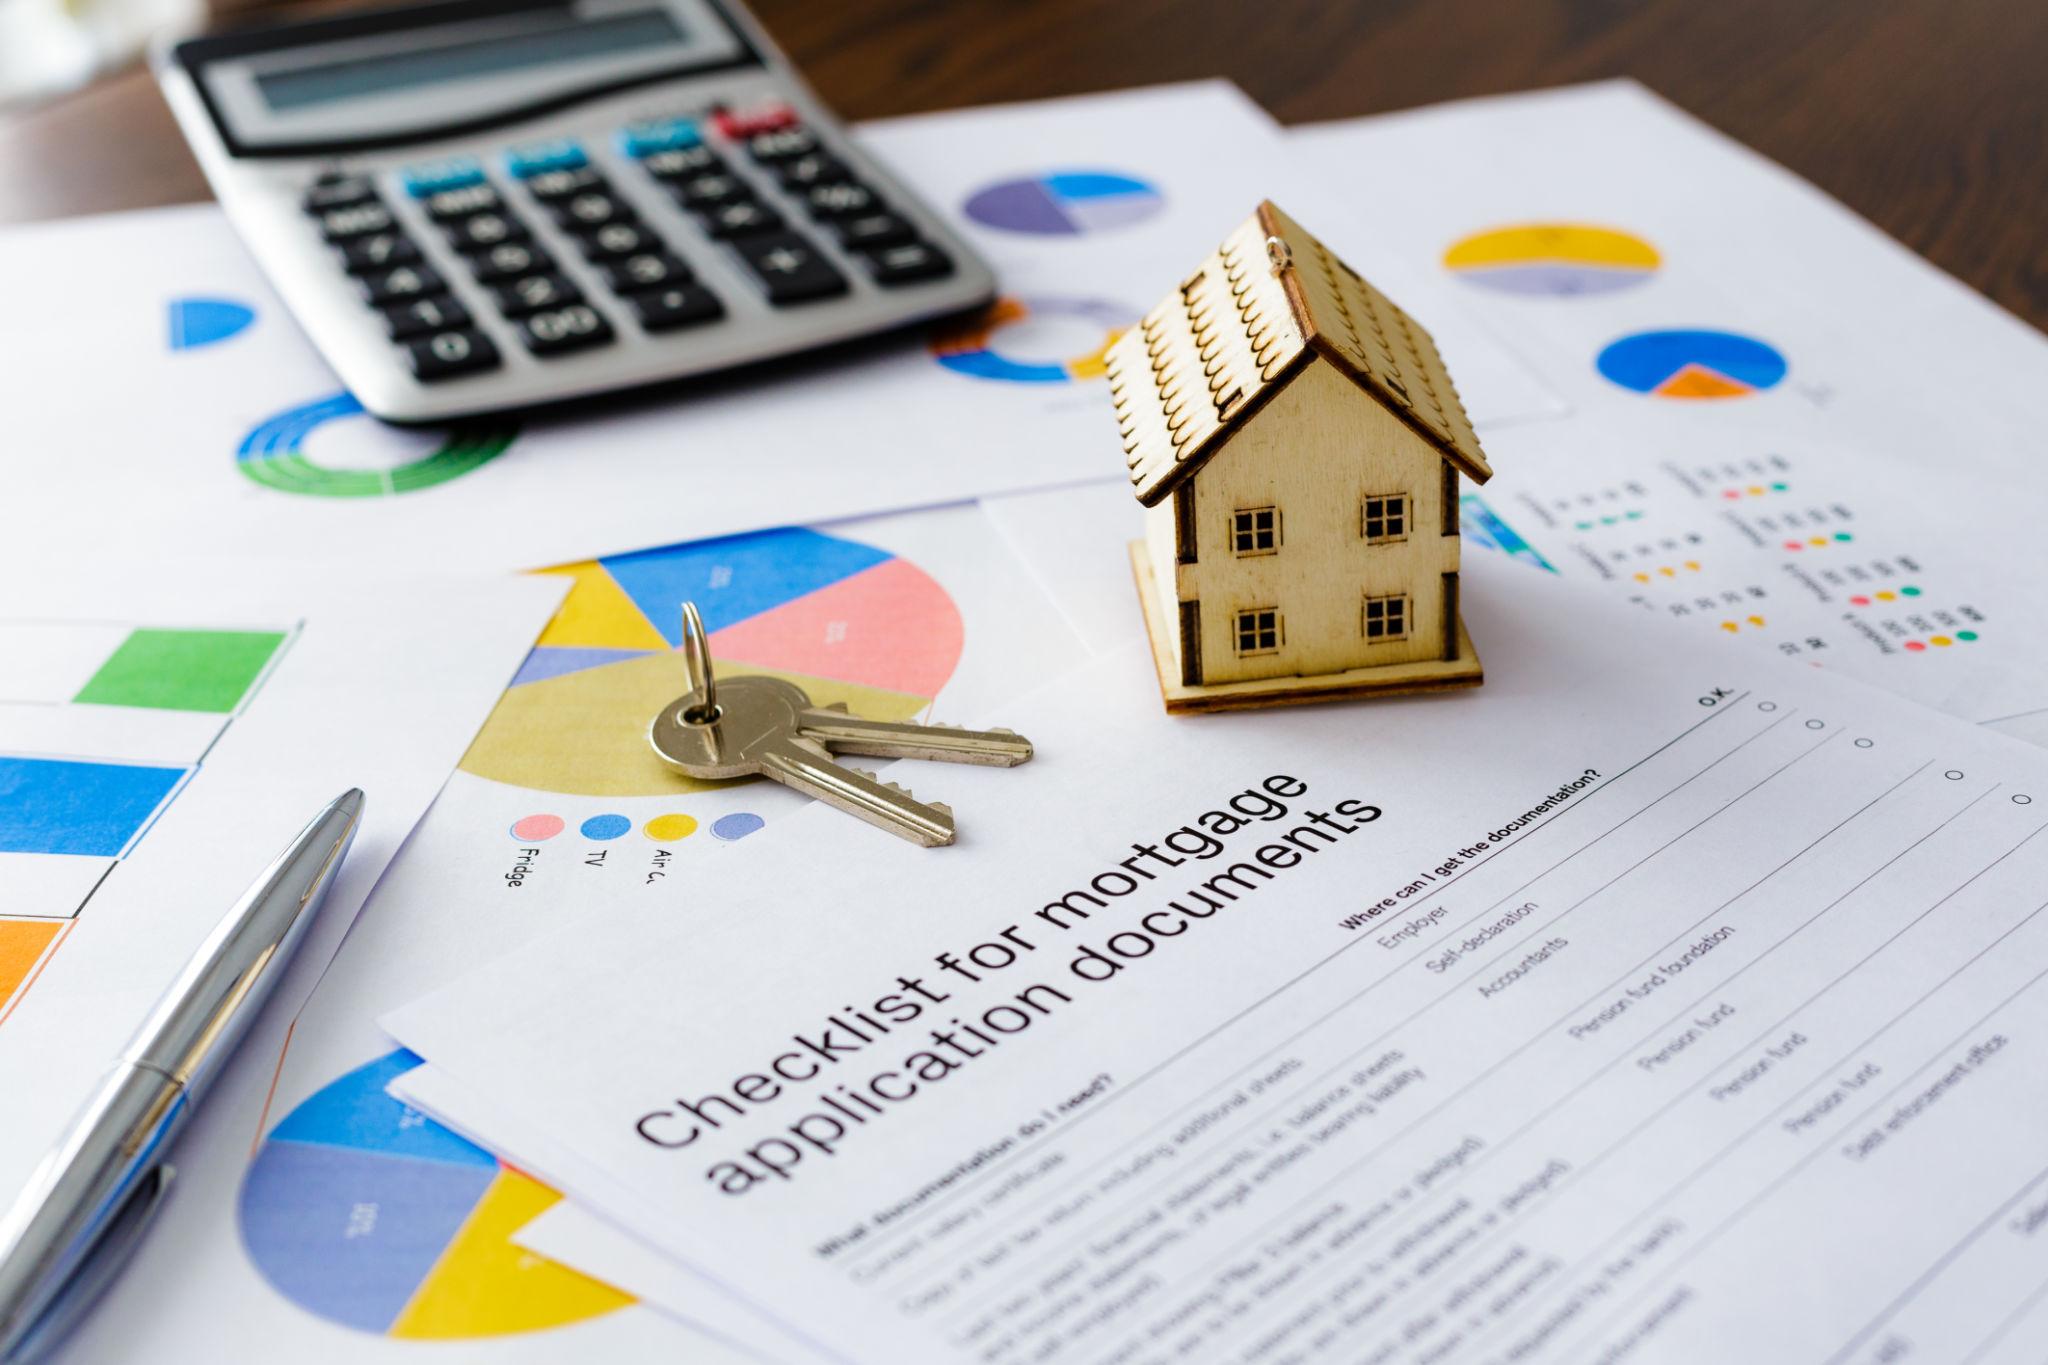
Documents That Speed Up Approval
Having the required documents ready can help make the home loan application process smoother.
- Latest 3–6 months' salary slips or applicable income-tax documents for self-employed applicants
- Recent bank statements showing salary credits or business income
- Property documents such as sale agreement, approved layout plan, and applicable project registration details
- PAN, Aadhaar, and address proof
- Existing loan statements showing current EMI obligations, if applicable
- Employment or business-related income documents requested by the lender
Exact documentation requirements can vary between lenders and borrower profiles, so confirm the current checklist with your chosen bank or financial institution.
Practical Steps to Improve Your Rate Before You Apply
Start preparing your finances several months before applying for a home loan.
Reducing existing high-interest debt can improve your monthly cash-flow position and may increase your overall borrowing capacity.
Review your credit report and correct any inaccurate information before submitting your application. Maintaining timely repayments on existing credit facilities is also important.
Avoid making numerous loan applications within a short period. Multiple hard credit enquiries can affect your credit profile, depending on the credit bureau and circumstances.
You can also compare loan offers from banks where you already maintain a salary account or banking relationship, as some lenders may provide relationship-based offers subject to their eligibility criteria.
Pre-Application Checklist
- Credit report checked and inaccurate information disputed well before applying
- Existing high-interest debt reviewed and reduced where possible
- Down payment planned based on your finances and applicable loan-to-value requirements
- Fixed and floating interest-rate options compared based on your risk comfort
- Loan tenure compared based on both EMI and total interest payable
- At least two or three lenders compared on overall cost rather than headline interest rate alone
- Income, identity, banking, and property documents prepared in advance
Frequently Asked Questions
1. What factors affect home loan interest rates in Chennai?
Factors can include your credit score, income, employment or business stability, existing EMIs, loan amount, loan-to-value ratio, repayment tenure, property details, and the lender's applicable pricing.
2. How can I get a better home loan interest rate?
Maintaining a strong credit profile, reducing existing debt, making a suitable down payment, comparing multiple lenders, and maintaining proper financial documentation can help you seek more competitive loan terms.
3. Is a fixed or floating home loan rate better?
Neither option is universally better. A fixed rate can provide greater predictability, while a floating rate can change over time. Compare the available options based on your financial situation and comfort with interest-rate changes.
4. Does a higher down payment reduce the home loan burden?
Yes. A larger down payment generally means borrowing less money, which can reduce the loan principal and potentially lower the total interest payable over the loan period.
5. Should I choose a longer home loan tenure to reduce EMI?
A longer tenure can reduce the monthly EMI but may significantly increase the total interest paid. Compare different tenures before choosing the repayment period that best fits your monthly budget and long-term financial goals.
6. Can I get a home loan for a plot in Chennai?
Some lenders offer plot loans or loan products for eligible residential plots, subject to their individual policies, property approvals, borrower eligibility, and documentation requirements. Buyers should confirm the applicable loan structure directly with the lender.
Final Thoughts
Finding the right home loan is about more than choosing the lowest advertised interest rate. Credit score, down payment, loan tenure, loan-to-value ratio, lender charges, and repayment capacity can all influence the overall cost of borrowing.
Before purchasing a Chennai apartment or plot, compare multiple lenders, prepare your documents, understand the applicable interest-rate structure, and calculate the total repayment amount. Careful preparation can help you choose a loan that fits your financial plan more comfortably.